Best Money Apps for Building an Emergency Fund in 2026
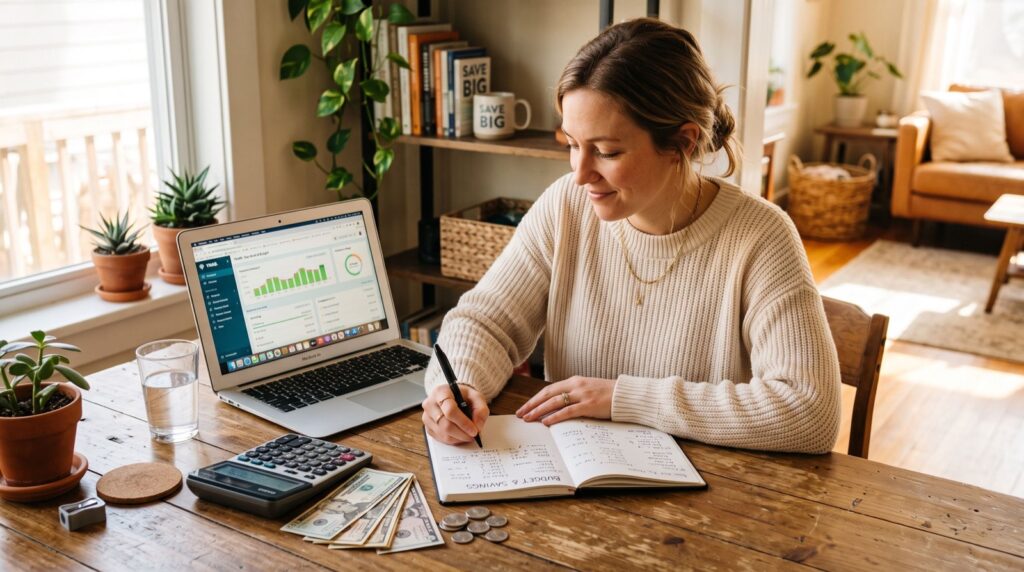
An emergency fund is the foundation every other financial goal rests on — and in 2026, the best money apps make building one almost effortless. Instead of relying on leftover cash that never seems to appear, these tools automate small, painless transfers that grow into a real safety net. This guide walks through how to use technology to build three to six months of expenses, even if you are starting from zero.
The need is real. Data from the U.S. Bureau of Labor Statistics Consumer Expenditure Survey shows that everyday costs continue to climb, which means a single car repair or medical bill can derail an unprepared household. A well-funded cushion turns those emergencies into inconveniences instead of crises.
What an Emergency Fund Actually Needs to Cover
Before choosing an app, define the target. An emergency fund exists to cover essential expenses when income stops or an unexpected bill lands. It is not a vacation fund or an investment account.
Your target should cover these essentials:
- Housing — rent or mortgage, plus insurance.
- Utilities — power, water, internet, and phone.
- Food — groceries, not restaurants.
- Transportation — fuel, transit, or car payments.
- Minimum debt payments — to protect your credit.
Add those up, multiply by three to six months, and you have your goal. The number can feel intimidating — which is exactly why automation matters.
How the Best Money Apps Accelerate Your Fund
Automated micro-transfers
Some apps analyze your income and spending, then move small “safe to save” amounts a few times a week. Because the amounts flex with your cash flow, you build savings without ever feeling squeezed.
High-yield savings integration
The best apps park your fund in an FDIC-insured, high-yield account so it earns interest while staying instantly accessible. Your emergency money should never be locked away or exposed to market risk.
Goal tracking and visual progress
Watching a progress bar fill is surprisingly motivating. Milestone alerts — 25%, 50%, fully funded — keep you engaged through the slow middle stretch.
Round-ups and windfall rules
Round-up features and “save my tax refund” rules quietly funnel extra dollars into the fund without touching your regular budget.
Comparison: Where Should Your Emergency Fund Live?
| Account type | Access speed | Typical yield (2026) | Emergency-fund fit |
|---|---|---|---|
| High-yield savings | 1–2 days | 3.5%–4.5% | Excellent |
| Checking account | Instant | 0%–0.5% | Poor (too tempting) |
| Money market | 1–3 days | 3%–4% | Good |
| Certificate of deposit | Locked term | 4%–5% | Poor (not liquid) |
| Brokerage/investments | 2–4 days | Variable | Poor (market risk) |
A Step-by-Step Plan to Fund Your Safety Net
- Set a starter goal of $1,000. This covers most small emergencies and builds momentum fast.
- Open a separate high-yield account so the money is out of sight and out of mind.
- Automate a weekly transfer — even $20 a week is over $1,000 in a year.
- Turn on round-ups to add spare change on autopilot.
- Redirect windfalls — tax refunds, bonuses, and gifts go straight to the fund.
- Increase the transfer each time you get a raise, before lifestyle creep absorbs it.
To compare tools side by side, start with a trusted list of the best money apps, which ranks them by automation and yield. Pairing the right app with a few proven personal finance tips keeps your fund growing steadily. If you would rather have the whole system built and monitored for you, dependable specialists can configure your accounts and automations end to end.
Is It Better to Save or Pay Off Debt First?
This is the question that stalls most people. The practical answer for 2026: build a small $1,000 starter fund first, then attack high-interest debt aggressively, and only afterward finish the full three-to-six-month fund. A tiny cushion stops a surprise expense from pushing you deeper into debt while you pay it down.
High-interest credit card debt often costs more than 20% a year, so eliminating it usually beats saving beyond that starter amount. But going straight to zero savings while attacking debt leaves you one flat tire away from a new balance.
An Original Tip: The Invisible Raise Trick
When you pay off a loan or a subscription ends, redirect that exact payment amount into your emergency fund automatically — the same day. You were already living without that money, so you will not miss it, and your fund suddenly grows faster with zero lifestyle sacrifice. I have watched this single trick add months of expenses to a savings balance within a year.
How Long Does It Take to Build a Full Fund?
The honest answer depends on your income, expenses, and how aggressively you automate. But the math is more encouraging than most people expect. Suppose your essential monthly expenses total $2,500, making your six-month target $15,000. That figure looks daunting until you break it into automated pieces.
Automate $200 a week and you reach the goal in roughly 18 months of transfers alone. Add round-ups averaging $30 a month, redirect a $1,500 tax refund, and apply the invisible raise trick after a loan ends, and you can shave four to six months off that timeline without changing your lifestyle at all. The point is not speed — it is inevitability. Once the automation is running, the fund fills whether you think about it or not.
Track your progress monthly rather than daily. Checking too often makes the balance feel stuck, while a monthly review shows clear, motivating movement. Celebrate each milestone, then let the system keep working.
Frequently Asked Questions
How much should my emergency fund hold in 2026?
Aim for three to six months of essential expenses. Single-income households or freelancers with variable income should target the higher end for extra security.
Which is the best money app for a beginner saver?
Look for an app that combines automated micro-transfers with an FDIC-insured high-yield account and clear goal tracking. That trio makes starting effortless and keeps your fund both safe and liquid.
Should my emergency fund be invested for higher returns?
No. Emergency money must stay liquid and protected from market swings. A high-yield savings account offers a solid return without risking the balance you may need overnight.
How do I stay motivated during the slow middle?
Use milestone alerts, automate everything so progress happens without effort, and redirect every windfall. Seeing the balance grow on its own keeps the habit alive.
Final Thoughts
An emergency fund is the difference between a stressful year and a stable one. The best money apps in 2026 remove the friction by automating transfers, maximizing yield, and keeping your goal front and center. Start with a $1,000 target this month, automate a weekly transfer, and use the invisible raise trick whenever a bill disappears. Your future self will thank you the next time life throws a surprise your way.